 By
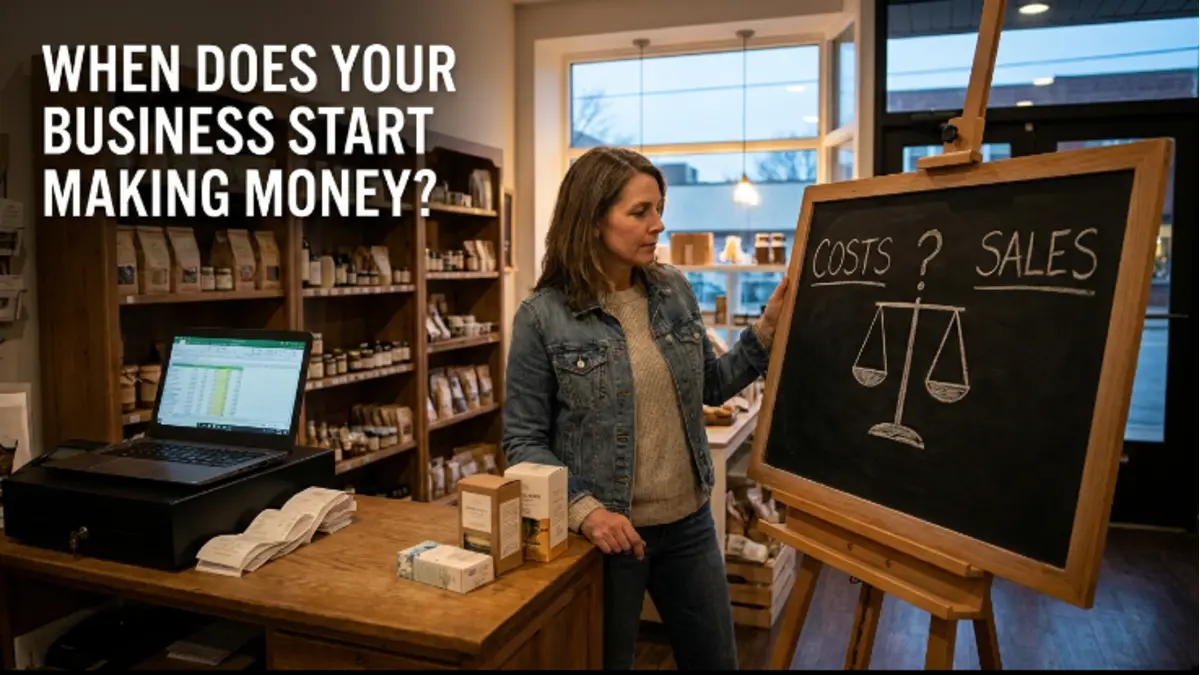
Before you can know How to Calculate Break Even Point for Small Business whether your small business is making money, you need to know how much it has to sell just to cover its costs. That number is your break even point.
The Break even point tells you how many products or services you need to sell, or how much revenue you need to generate, before your business stops losing money. Once you sell beyond that point, you start generating a profit.
The calculation is simpler than it sounds. You mainly need three numbers: your fixed costs, variable cost per sale, and selling price.
What Is the Break-Even Point?
The break-even point is the point where your total revenue equals your total costs.
At break-even:
Revenue = Total Costs
You are not making a profit, but you are not losing money either.
For a small business, knowing this number can help with pricing, sales targets, budgeting, hiring decisions, and deciding whether a new product or service is financially worthwhile.
For example, suppose you sell a product for $50. After paying the costs directly associated with making or purchasing each unit, you keep $30 to help cover your monthly business expenses.
If your monthly fixed costs are $3,000, you would need to sell 100 units to break even.
Everything sold after those first 100 units contributes toward profit, assuming your costs and selling price remain the same.
Break-Even Point Formula
For a business selling one type of product, the basic formula is:
Break-even point in units = Fixed Costs ÷ (Selling Price per Unit − Variable Cost per Unit)
The amount inside the parentheses is called your contribution margin per unit.
So you can also write the formula as:
Break-even point = Fixed Costs ÷ Contribution Margin per Unit
Example
Imagine you run a small candle business.
| Item | Amount |
|---|---|
| Selling price per candle | $25 |
| Variable cost per candle | $10 |
| Monthly fixed costs | $3,000 |
| Contribution margin | $15 |
Now calculate:
$3,000 ÷ ($25 − $10) = 200 candles
You need to sell 200 candles per month to break even.
At 200 candles:
- Revenue = $5,000
- Variable costs = $2,000
- Fixed costs = $3,000
- Profit = $0
If you sell 250 candles, the additional 50 candles generate $750 in contribution margin.
So, before taxes and any other costs not included in the calculation, your operating profit would be $750.
How to Calculate Break Even Point for Small Business (Step by Step)
Step 1: Calculate Your Fixed Costs
Fixed costs are expenses that generally do not change directly with the number of products or services you sell.
For a small business, these might include:
- Rent
- Business insurance
- Software subscriptions
- Salaried administrative staff
- Accounting fees
- Website and hosting costs
- Equipment leases
- Certain loan payments
- Professional services
Suppose your monthly fixed expenses look like this:
| Expense | Monthly Cost |
|---|---|
| Rent | $1,500 |
| Insurance | $200 |
| Software | $150 |
| Administrative costs | $650 |
| Other fixed expenses | $500 |
| Total fixed costs | $3,000 |
Your fixed-cost figure for the break-even calculation would be $3,000 per month.
Be careful not to automatically classify every expense as fixed. Some costs can contain both fixed and variable components.
Step 2: Calculate Your Variable Cost Per Unit
Variable costs change as you sell more products or provide more services.
For a physical product, variable costs might include:
- Product materials
- Wholesale product cost
- Packaging
- Per-order payment fees
- Shipping costs paid by the business
- Sales commissions
Suppose your candle costs $10 in materials, packaging, and other costs directly tied to each sale.
Your variable cost per candle is therefore $10.
If you sell 100 candles, those variable costs would be approximately $1,000.
Step 3: Determine Your Selling Price
Next, determine how much the customer pays for one unit.
Let’s use the same $25 candle.
Your numbers are now:
Selling price: $25
Variable cost: $10
Contribution margin: $15
That $15 is what each candle contributes toward covering your fixed costs.
Once your fixed costs have been covered, additional contribution margin can become operating profit.
Step 4: Calculate Your Break-Even Point
Now put the numbers into the formula:
$3,000 ÷ ($25 − $10) = 200 units
Your break-even point is therefore 200 candles per month.
That gives you a much more useful sales target than simply saying, “We need to sell more.”
You now know exactly what “enough sales” means under these assumptions.
How to Calculate Break-Even Sales in Dollars
Sometimes a business doesn’t sell one simple product, or it is more useful to think in terms of revenue rather than units.
You can calculate the break-even point in sales dollars using the contribution margin ratio.
Break-even sales = Fixed Costs ÷ Contribution Margin Ratio
The contribution margin ratio is:
(Selling Price − Variable Cost) ÷ Selling Price
Using the candle example: ($25 − $10) ÷ $25 = 60%
Then: $3,000 ÷ 0.60 = $5,000
So the business needs approximately $5,000 in monthly sales to break even.
Break-Even Point Example for a Service Business
Break-even analysis isn’t limited to stores or product-based businesses.
Suppose you run a small marketing agency.
You charge an average of $1,000 per client each month. After accounting for freelancer costs, payment fees, and other expenses that increase with each client, your variable cost is $300 per client.
Your monthly fixed costs are $7,000.
Your contribution margin per client is: $1,000 − $300 = $700
Your break-even point is: $7,000 ÷ $700 = 10 clients
You need approximately 10 clients per month to break even under these assumptions.
This can make planning much easier. Instead of setting an arbitrary client goal, you can see the minimum number of clients required to cover your costs.
What If Your Business Sells Multiple Products?
This is where break-even analysis becomes a little more complicated.
A clothing store, grocery store, electronics shop, or online retailer may sell hundreds of products at different prices and margins.
You can’t simply use one product’s break-even point for the entire business unless that product represents the business’s overall sales mix.
Instead, you can calculate a weighted average contribution margin based on the products you typically sell.
For example:
| Product | Price | Variable Cost | Contribution Margin |
|---|---|---|---|
| Product A | $40 | $20 | $20 |
| Product B | $60 | $30 | $30 |
| Product C | $100 | $55 | $45 |
If your sales mix stays reasonably consistent, an average contribution margin can help you estimate the overall break-even point.
For a business with a large number of products, using accounting or spreadsheet software can make this calculation easier.
Why Break-Even Analysis Matters for Small Businesses
Break-even analysis is useful because it turns business expenses into a sales target.
It can help you answer practical questions such as:
How many products do I need to sell each month?
Can my current price cover my costs?
What happens if my rent increases?
How much would lowering my price affect the number of sales I need?
Can I afford to hire another employee?
How many clients do I need before a new service becomes profitable?
It can also expose problems that aren’t obvious from revenue alone.
A business might generate $20,000 in monthly sales and still struggle because its variable costs and fixed expenses are too high.
Revenue by itself doesn’t tell you whether the business is financially sustainable.
How Pricing Changes Your Break-Even Point
Your selling price has a direct effect on your break-even point.
Suppose your fixed costs are $3,000 and your variable cost is $10.
At a $25 selling price:
$3,000 ÷ ($25 − $10) = 200 units
Now imagine you lower the price to $20.
Your calculation becomes:
$3,000 ÷ ($20 − $10) = 300 units
You would now need to sell 300 units instead of 200 to break even.
This is why a discount can increase sales volume without necessarily improving profitability.
Before changing prices, look at the contribution margin rather than revenue alone.
How to Lower Your Break-Even Point
There are three basic ways to reduce the number of sales you need to break even.
Reduce fixed costs
Review recurring expenses and determine whether every expense is necessary.
This could mean renegotiating rent, removing unused software subscriptions, reducing unnecessary overhead, or finding more efficient service providers.
Reduce variable costs
Look at supplier pricing, packaging, production methods, payment fees, and shipping costs.
Even a small reduction in variable cost can improve your contribution margin.
Increase your selling price
If customers are willing to pay more and the market supports it, a higher price increases your contribution margin.
But pricing should be based on customer demand, competition, perceived value, and your overall business strategy rather than simply raising prices to improve a spreadsheet calculation.
What Is a Good Break-Even Point?
There is no universal break-even number that is automatically good or bad.
It depends on the size of the business, industry, margins, sales volume, operating costs, and available cash.
What matters is how realistic the required sales level is.
If your business needs to sell 1,000 units every month to break even but your current sales average only 500, you have a significant gap to address.
If your business normally sells 1,500 units, you have more room between your typical sales level and the break-even point.
That difference is your margin of safety.
Break-Even Point vs. Profit Target
Breaking even should not be your final business goal.
You can also use the same formula to determine how much you need to sell to reach a specific profit target.
The formula becomes:
Required Units = (Fixed Costs + Desired Profit) ÷ Contribution Margin per Unit
For example, if your fixed costs are $3,000, your contribution margin is $15, and you want $1,500 in profit:
($3,000 + $1,500) ÷ $15 = 300 units
You would need to sell 300 units to cover your costs and reach the $1,500 profit target.
This is often more useful for business planning than simply calculating break-even.
Common Break-Even Calculation Mistakes
The formula itself is simple. The numbers going into it are where mistakes usually happen.
Don’t forget costs that occur regularly but aren’t obvious on a daily sales report.
Don’t treat every expense as completely fixed or completely variable when it actually changes with sales.
Don’t assume your current sales mix will stay exactly the same forever.
And don’t use break-even analysis as a substitute for cash-flow planning. A business can be profitable on paper and still experience cash-flow problems because of payment timing, inventory purchases, debt payments, or other cash requirements.
Break-even analysis is a planning tool, not a complete financial forecast.
Frequently Asked Questions
What is the easiest way to calculate a break-even point?
Use the formula: Fixed Costs ÷ (Selling Price − Variable Cost Per Unit)
The result tells you approximately how many units you need to sell to cover your costs.
Can I calculate break-even if I don’t sell physical products?
Yes. Service businesses can use the same concept. Instead of units of a product, you can calculate the number of clients, projects, appointments, or billable hours needed to cover your costs.
What happens if my break-even point is higher than my current sales?
It means your current sales volume isn’t enough to cover all the costs included in your calculation. You may need to increase sales, improve your contribution margin, reduce costs, change pricing, or adjust the business model.
Should I include taxes in my break-even calculation?
It depends on what you are trying to measure. A basic operating break-even calculation usually focuses on the costs required to operate the business. If you’re planning for a specific after-tax profit target, taxes can be incorporated into a more detailed financial model.
Can a business have more than one break-even point?
Yes. Businesses with multiple products, changing cost structures, seasonal operations, or different sales channels may have different break-even scenarios. A single calculation may not accurately represent every situation.
Final Takeaway
Calculating your break-even point gives you one of the clearest answers a small-business owner can have: how much do I actually need to sell before this business starts making money?
Start with your fixed costs, determine the variable cost associated with each sale, calculate your contribution margin, and then apply the formula.
Once you know the number, don’t stop there. Use it to set realistic sales targets, review pricing, control expenses, and plan for a profit rather than simply trying to generate more revenue.
A break-even calculation won’t tell you everything about your business, but it can give you a much clearer financial starting point for making better decisions. If you want learn about How to Increase sales in retail, read this guide.